Prediction markets · Brief · 7 min read
Prediction markets: a build checklist for staying inside the passive-software letter
The ten conditions of CFTC Staff Letter 26-25 turned into product and contract questions, in the order a team meets them: the team, the product, the registrant, onboarding, disclosures, marketing, records and filings.
CFTC Staff Letter 26-25 gives passive software providers a no-action position on ten conditions. The conditions are written for lawyers; a team builds from questions. This checklist follows the order in which a team meets the conditions, and under each question gives the letter’s words. The deep dive on the Phantom letter explains what the position is and is not. A staff position runs until the Commission acts and the Division can modify it, so each item below is a fact to establish and record.
1. The team and the product
- Has everyone who will solicit users, and every principal, been checked for statutory disqualification? Condition 1 asks that the provider, its principals and any individual soliciting users are not subject to it, absent a waiver, and that the Division is told promptly if that changes.
- Does the product only show data, show positions and send the user’s orders from the user’s device to a registrant? The letter describes software “on the User’s device”.
- Does any feature generate a buy or sell signal, hold or control user assets, or decide where an order goes or when it executes? The letter says the provider does none of the three.
- If the product sits inside an existing wallet or app, does the interface say, clearly and conspicuously, when the user is engaged in regulated activity and when not?
The PSP will offer this proposed User interface either as a standalone product or as an embedded feature of its existing wallet software, if any. In the latter case, the PSP’s software interface would clearly and conspicuously distinguish when a User is engaging in Commission-regulated activity or not. … At no point would the PSP hold, control, or take into custody User assets, generate express “buy” or “sell” signals, or exercise discretion with respect to the routing or execution of User orders.
2. The registrant and the user’s account
- Which registrant is the counterparty: the exchange, a futures commission merchant or an introducing broker? Its rules decide what it will sign, and condition 7 cannot be met without it.
- Is the user onboarded as a direct member of the exchange or a customer of the broker, and can the user reach the registrant without the product? Condition 4 asks for both.
- Is the undertaking drafted and signed with each registrant before launch, and is each one filed with the Division?
Users are onboarded as direct members (for DCMs) or customers (for registered FCMs and IBs), and they continue to have the ability to access the respective Registrant independently of the PSP. … The PSP and each of its Registrants execute in writing an undertaking by which they each agree to be jointly and severally liable for any violations of the Act or Commission regulations by the PSP or any of its personnel when the PSP or its personnel engage in the Covered Activities with or on behalf of such Registrant. … The PSP files each of these undertakings with the Division.
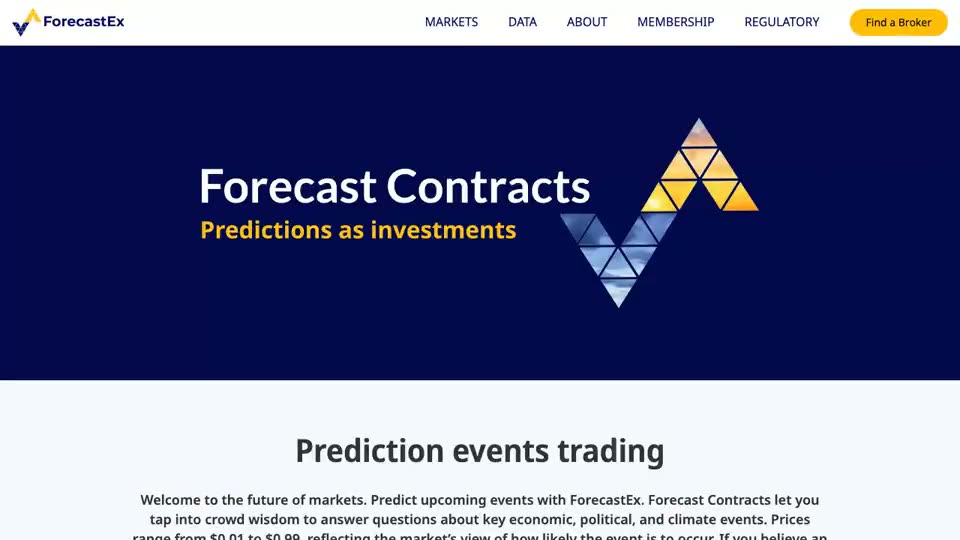
ForecastEx’s public site: contracts priced as Yes and No percentages, a box telling visitors to trade “with one of the qualified Future Commission Merchants (FCM)”, then the broker page listing Interactive Brokers, Robinhood and Advantage Futures. The exchange lists the contract; the customer arrives through an FCM.
3. What the user is told
- Does each user receive, and acknowledge, a disclosure of the provider’s relationship with each registrant, including conflicts and fees? Condition 2.
- Does each user receive and acknowledge a risk disclosure covering the risks in Regulation 1.55(b), to the extent relevant, with the acknowledgement recorded? Condition 3 applies unless the registrant is registered and already gives the disclosure.
- Is the acknowledgement stored in a way that can be produced later? Condition 3 says the provider “shall retain a record”.
The PSP provides, and each User acknowledges receipt of, disclosures regarding the PSP’s relationship with the relevant Registrant(s), addressing potential conflicts of interest (including fees). … The PSP provides, and each User acknowledges receipt of, a risk disclosure statement addressing the risks covered by the risk disclosure statement contained in Commission Regulation 1.55(b), … to the extent relevant to the trading activity facilitated by the PSP. The PSP may provide this disclosure as part of its terms of service or other User onboarding documentation, provided that the PSP shall retain a record of the User’s acknowledgement of the disclosure.
A public page is one place a line on availability, fees and loss appears. Phantom’s Prediction Markets page carries one:
Prediction markets in Phantom are not available in all jurisdictions. Trading prediction markets may incur transaction fees and other costs. If your prediction is incorrect, you may lose the entire amount you allocate to an event.
The letter asks for an acknowledged disclosure and a record of it. This brief does not read any product’s pages against the letter.
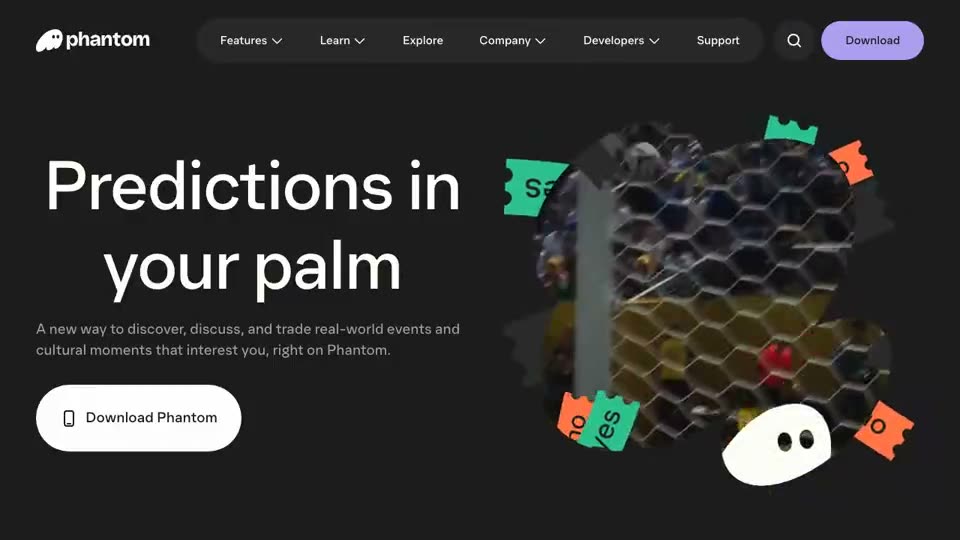
A wallet front end for event contracts: Phantom’s public Prediction Markets page shows in-app screens with a basketball game priced in percentages and a “Make your prediction” control, then opens the FAQ answer stating that its markets are powered by Kalshi via DFlow and that users do not open a Kalshi account.
4. Marketing
- Is there a written policy for communications with the public and marketing, set as if the provider were registered as an introducing broker, and a review step that enforces it? Condition 5.
- Is there a list of promotional formats the team does not run, namely any that would need NFA pre-approval under Compliance Rule 2-29 for a registered firm? Condition 6.
- Who pre-approves and supervises what staff say at conferences and on social media? The letter’s footnote on personnel says those statements are “subject to the PSP’s pre-approval and supervision”.
The PSP does not engage in advertising or promotions that, if the PSP were registered as an IB, would require pre-approval by NFA under NFA Compliance Rule 2-29. … Activity by relevant personnel would involve discussing and demonstrating the PSP’s software offering at industry conferences and other events, as well as making promotional statements on social media, in each case subject to the PSP’s pre-approval and supervision.
5. Records, notices and the filing
- Are records of compliance with the conditions, and of the regulated business, kept consistent with Regulation 1.31? Condition 8.
- Is there a trigger that sends notice to the Division if the company becomes insolvent or enters bankruptcy? Condition 9.
- Has the notice agreeing to the conditions and consenting to the Commission’s jurisdiction been prepared for filing, and is a waiver of sovereign immunity included if the provider is tied to a state or tribal government? Condition 10 and its footnote.
- Is every document addressed as the letter directs, and does it reference the letter?
The PSP maintains records regarding its compliance with these conditions and its business involving Commission-regulated activity in a manner consistent with Commission Regulation 1.31. … The PSP provides notice to the Division if the entity becomes insolvent or enters a bankruptcy proceeding. … The PSP files a notice with the Division agreeing to satisfy these conditions and consenting to the Commission’s jurisdiction to investigate and take enforcement action against the PSP for any violation of the Act or Commission regulations in connection with the Covered Activities engaged in by the PSP or any of its personnel. … Each document or notice required to be submitted under these conditions to the Division must be sent to the MPD Director via email to MPDLetters@cftc.gov and referencing this letter.
The letter states no fee, form or deadline for the notice.
What a builder does with this
- Build the checklist into the release process: each item is a yes or a recorded no before the product goes live, and a change to the product re-opens the items it touches.
- Put the contract steps first on the calendar. The undertaking and the onboarding design depend on a registrant, and neither can be finished by the provider alone.
- Keep evidence, not intentions: the signed undertakings, the acknowledgement logs, the marketing policy and its review records, and the filings, in one place.
- Treat any feature that signals, holds funds or routes as a change to the facts the position rests on, and take it to a registered path or leave it out of the first release.
- Re-read the letter at each release. The Division can modify or end its position, and the checklist is only as current as the letter.